- Locations
- Interviews
- Luxury Home
- Luxury Lifestyle
- Luxury Travel
- Luxury News
- Events
- More
- Magazine

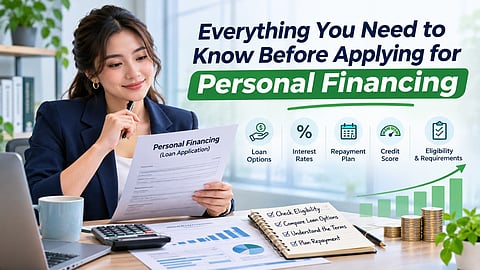
Getting personal financing is necessary, because there are always situations when you need more money. And thankfully, you can find solutions to focus on, especially these days. But with so many different financing options, it’s important to know which one is ideal for you. There are pros and cons for all of them, and here’s what you want to know.
The great thing about personal financing is that you can find a variety of options these days. It’s up to you to perform your due diligence and see which option delivers what you’re looking for. Thankfully, there are a variety of solutions these days, so you can easily pick and choose what works.
Credit cards are a very common option because they involve revolving credit with variable payments and higher interest rates.
Lines of credit allow you to draw funds as you need up to a limit and you pay interest solely on what you use.
Then, there are the secured loans, like auto loans or the home equity loans that offer a lower rate because the lender holds some type of collateral.
And then, we have the payday and short term loans. These are quick and easy to obtain, yet the interest rates are much higher, thus making them extremely challenging for most people.
It depends on the person and what you want to use the money for. Generally, financing makes sense only if you really need something. For example, borrowing for emergency repairs is a need, but purchasing an RTX 5080 graphics card for your gaming computer is a want. It’s a good idea to borrow money only for something you really need.
Another thing to consider is whether you can wait and save. If you do, then it makes a lot of sense to save instead of borrowing. Check for a simpler alternative as the options can include negotiating a payment plan, borrowing from family, using a 0% promotional credit and other things of that nature.
Before you delve into personal financing, you want to make bank statements and see your existing financial situation. That will help you narrow down how much you can afford borrowing. It’s why you want to check your credit report first and understand what drives your score. Knowing the rough tiers is a great idea too, just to be safe.
Additionally, you need to understand that companies won’t just borrow money to help you. They will apply interest, in some cases the interest rates being extremely high. And there are both fixed rates, but also variable rates that change overtime. Another thing you have to focus on would be the loan term. In many of these cases, loans can be short, but there are also long-term loans as well.
Plus, there can be additional charges or fees, too. The problem here is that there are origination fees which are deducted from the funds you receive. There are also late payment fees, in case you don’t repay on time. Prepayment penalties can be applied as well, and you will have application or processing fees. It doesn’t seem like a lot, but plenty of fees apply, so making sure you know which fees apply does matter. You can end up paying quite a bit extra due to fees alone.
Whether you freelance or you are hired by a business, you have monthly income. The thing is, when you apply for financing, you want to know what’s your existing budget. That means you want to list your monthly income, list the fixed obligations, estimate variable spending and subtract it all to see what remains. Avoid setting a high budget that you can’t stick with during the loan’s duration, as it will make it difficult to repay the loan. Alternatively, you can prolong the loan’s timespan, although that will increase the amount you pay.
It’s a no-brainer, but it does make a lot of sense to try and shop around to see the various loan options. Compare offers side by side to see where you are getting the best deal, and try to use prequalification as well. It also helps if you consider the different lender types. A traditional bank could offer existing customer discounts. Credit unions tend to deliver lower rates, but you have to be a member. And then there are online lenders, that offer streamlined applications and fast decisions, yet their rates might vary. So yes, there are options, you just have to pick the right option.
Clearly, when someone is in dire need of money, they can easily be pushed into predatory loans, and there are many unscrupulous companies willing to take advantage of that. How can you identify those lenders? Here are some tips:
Guaranteed approval regardless of the credit history is a red flag, as most companies won’t do that.
Demanding upfront fees before the loan is issued is another major red flag.
They might also pressure you to sign very fast, something that can be very problematic.
The same thing can be said about vague or missing disclosures of the APR and the total repayment amount.
Unsolicited offers by phone, social media or text matter as well.
And then there are also lenders unwilling to provide written terms, which is another major red flag.
If you want to use personal financing options, you always want to read the agreement before you sign and understand what collateral you need to provide. While most financing companies are genuine and offer transparency, there are also plenty of lenders that will try to take advantage of you. That’s why you have to perform your due diligence, understand the lender’s history and check their reviews. It will give you a good idea of what to expect and how the lender operates. Don’t rush into any personal financing option, instead study every option, compare interest rates, and then pick the ideal one.
Inspired by what you read?
Get more stories like this—plus exclusive guides and resident recommendations—delivered to your inbox. Subscribe to our exclusive newsletter
The products and experiences featured on RESIDENT™ are independently selected by our editorial team. We may receive compensation from retailers and partners when readers engage with or make purchases through certain links.