- Locations
- Interviews
- Luxury Home
- Luxury Lifestyle
- Luxury Travel
- Luxury News
- Events
- More
- Magazine

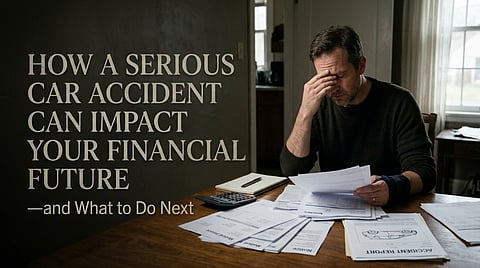
A serious car accident can change your financial future long after your vehicle is repaired. Medical bills may arrive while you are missing work, and injuries can make your old job difficult or impossible to perform.
The financial damage often grows beyond the first hospital bill or insurance deductible. Protecting your future means understanding how those costs overlap, keeping clear records and getting help before making decisions that could leave you paying for years.
Emergency treatment is only the beginning of the medical costs you may face. Follow-up appointments, physical therapy, prescriptions and transportation to treatments can keep adding expenses while your household bills continue.
Even with health insurance, deductibles and other out-of-pocket costs can put pressure on your budget. You might start using money meant for rent, a home purchase or your children’s education just to keep up with immediate expenses.
According to research by the Federal Reserve, only 63% of adults surveyed in 2024 said they would cover a $400 emergency expense using cash or its equivalent.
If your savings are limited, even a relatively small accident-related bill can force difficult choices between treatment and everyday needs.
Credit cards and payment plans may help cover bills today, but they can create obligations that outlast your recovery. Interest charges make borrowing especially costly when you cannot predict when your income will return.
Also, the Consumer Financial Protection Bureau explains that certain unpaid medical debts can appear on credit reports, subject to reporting restrictions. So, review bills, confirm insurance payments and address errors rather than assuming every medical balance is excluded.
And ask providers about financial assistance or payment arrangements before putting medical expenses on a credit card. Keep copies of those agreements so you can track what you owe.
Missing several paychecks can destabilize a household budget even when medical expenses are manageable. Paid leave may run out, while overtime, tips or self-employment income may disappear immediately.
The larger problem is sometimes reduced earning ability rather than temporary unemployment. An injury might prevent you from lifting equipment, driving for work or maintaining the concentration your job requires.
For example, traumatic brain injuries can affect work and may require changes such as shorter schedules or modified duties. If your recovery involves those limitations, returning to work may not mean returning to your previous income.
A lower paycheck can leave less room for retirement contributions, professional training or saving for a home. Using retirement funds to cover current expenses also reduces the money available for future growth.
Career changes can bring their own costs, including retraining or accepting an entry-level position in another field. Those possibilities deserve attention when evaluating the full financial impact of your injuries.
Write down how your work has changed, including reduced hours, missed advancement opportunities and duties you can no longer perform. Pair those notes with employer records and medical guidance rather than relying on memory months later.
Start by getting appropriate medical care and notifying the relevant insurers about the accident. Avoid guessing about injuries or making promises about when you will return to work.
One of the best things you can do to attain a solid financial future after a serious car accident is to contact a lawyer. A legal professional could help you pursue maximum compensation.
Look for an experienced lawyer in your local area. Choosing a local lawyer gives you access to someone familiar with your area’s courts and makes it easier to meet in person as your case progresses.
For example, if you are injured in Georgia, you could seek assistance from a Macon car accident injury lawyer that has local knowledge of Macon roads and courts.
Save medical bills, treatment plans, pay stubs, repair estimates and receipts for accident-related expenses. Include practical costs such as rides to appointments or paid help with tasks your injuries prevent you from doing.
Keep a simple running list with each expense, its date and supporting documentation. A clear record helps you explain how the accident affected your finances without scrambling to reconstruct everything later.
An early offer may look helpful when bills are piling up, but immediate expenses are only part of the picture. Before accepting, ask whether your medical outlook and work limitations are clear enough to evaluate future losses.
Read proposed settlement documents carefully and ask a lawyer to explain what accepting would mean for your claim. Continue budgeting conservatively while the claim is unresolved, since neither payment timing nor a particular outcome is guaranteed.
A serious car accident can affect your savings, income and long-term goals at the same time. Clear records and informed decisions can help you protect more than your next paycheck.
Was this article useful? If so, be sure to look at some of our other informative posts.
Inspired by what you read?
Get more stories like this—plus exclusive guides and resident recommendations—delivered to your inbox. Subscribe to our exclusive newsletter
The products and experiences featured on RESIDENT™ are independently selected by our editorial team. We may receive compensation from retailers and partners when readers engage with or make purchases through certain links.